Len Strickler, CEO
Managing PartnerLen works with fixed indexed annuities and principal-protection strategies, and is the author of Way of the Financial Warrior.
Read full bio →We'll explain how fixed index annuities work, the benefits and the trade-offs, so you can decide if one belongs in your plan.
Which part of your savings, if any, you'd want protected from market losses, and how much you need to keep liquid.
How interest is credited: the index, the cap or participation rate, and how those can change over time.
How long your money is committed, what surrender charges apply, and what you can withdraw each year without one.
Whether an income rider fits your income plan, and what its annual fee does to your contract value.
How tax deferral works and how withdrawals may be taxed, so there are no surprises.
Who stands behind the contract, since guarantees depend on the insurance company's claims-paying ability.
A fixed index annuity (FIA) is a contract with an insurance company. It isn't a bank deposit and it isn't a direct investment in the stock market. Instead, the interest it credits is linked to the performance of a market index, such as the S&P 500.
When the index rises, your contract may be credited interest up to a limit, set by a cap or a participation rate. When the index falls, a 0% floor is designed to keep your credited value from going down because of index losses. Guarantees are subject to the claims-paying ability of the issuing insurance company.
Caps and participation rates are set by the insurer and can change, usually at each renewal period.
An FIA is not right for everyone. Here's what you get, and what you give up.
An income rider is an optional add-on to an FIA. It's designed to provide a stream of income for life, starting when you choose, even if your contract value runs down, subject to the rider's terms and the insurer's claims-paying ability.
Riders usually carry an annual fee, often taken as a percentage. That fee reduces your contract value. The 'income base' a rider uses to calculate payments is not cash you can withdraw. We walk through the numbers so you understand what you're paying for.
An FIA may be worth a closer look if most of these sound like you. If they don't, that's useful to know too.
Len Strickler's book covers five financial self-defense moves to help protect your retirement income. Request your copy.
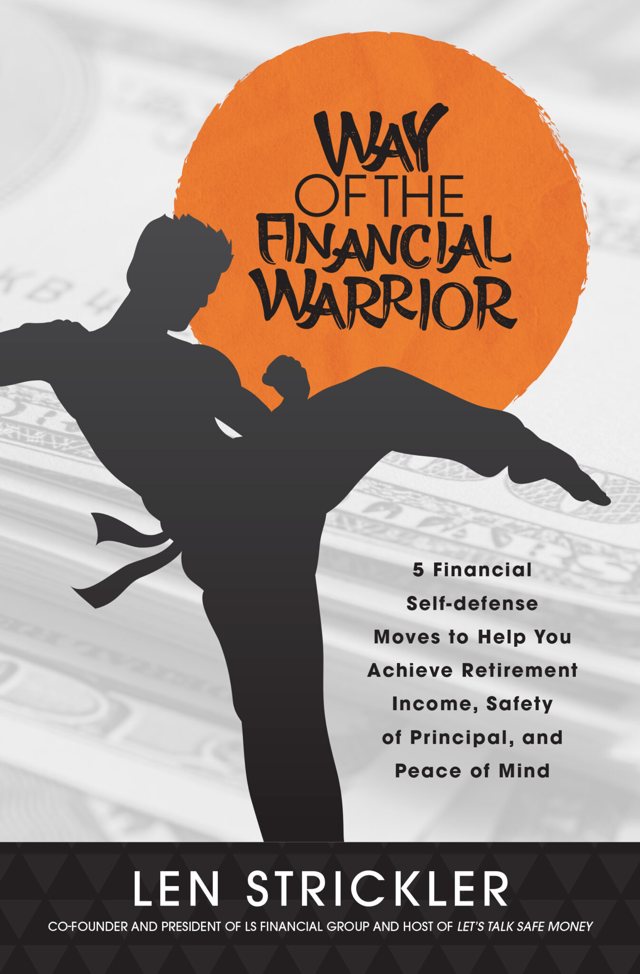
Five financial self-defense moves to help you pursue retirement income, safety of principal and peace of mind. By Len Strickler.
We post a printed copy to you from our Fort Lauderdale office.
Len works with fixed indexed annuities and principal-protection strategies, and is the author of Way of the Financial Warrior.
Read full bio →
Juan has 37 years of experience, is licensed in life and annuities, and builds retirement strategies on principal protection.
Read full bio →Claudine focuses on insurance solutions and works with Spanish-speaking clients.
Read full bio →John has 30 years in financial services and focuses on protecting accumulated wealth, so he can show where principal protection fits in your plan.
Read full bio →
Len and Art host the show on 610 WIOD. Watch more episodes in LSF University.
Watch full episodesA fixed index annuity is an insurance contract. Interest is credited based on the performance of a market index, up to a cap or participation rate, but your money isn't invested directly in the market. In years when the index falls, a 0% floor is designed to keep index losses from being credited to your contract.
Your principal is protected from market-index losses, and guarantees are subject to the claims-paying ability of the issuing insurance company. You can still lose value in other ways: surrender charges apply if you withdraw more than the free amount during the surrender period, and rider fees reduce your contract value. That's why we review those costs with you before anything is signed.
A surrender charge is a fee for withdrawing more than the contract allows, or cashing out, during the surrender period. The period often lasts several years, and the charge usually declines each year. Most contracts allow a limited penalty-free withdrawal each year. Terms vary by carrier and product, so we show you the schedule for any contract you're considering.
An income rider is an optional feature designed to provide lifetime income, subject to its terms and the insurer's claims-paying ability. It usually has an annual fee that reduces your contract value. The rider's income base is used to calculate payments and is not a cash value you can withdraw.
A CD is a bank deposit, FDIC insured up to applicable limits, with a fixed rate. A variable annuity invests in market subaccounts, so its value can go down with the market. An FIA is an insurance contract that credits interest linked to an index, with a 0% floor against index losses, but it is not FDIC insured and comes with surrender periods, caps and possible rider fees.
Growth in an annuity is generally tax-deferred until you take money out. Withdrawals of earnings are generally taxed as ordinary income, and withdrawals before 59½ may face an additional 10% federal penalty. Annuities held in an IRA follow IRA rules. This is general information, not tax advice for your situation; consult your tax professional.
Trafalgar Plaza, 5310 NW 33rd Ave., Suite 114, Fort Lauderdale, FL 33309 · In person, or by video from anywhere in the country
15 minutes, no obligation. Pick a time and we’ll call you, or meet us at Trafalgar Plaza or by video.